The Best Ways to Save Money Fast: A Complete Beginner’s Guide
.
Introduction
Let’s be real for a second. Checking your bank account shouldn’t feel like opening a horror movie script but lately, it does.
You get paid. You blink. And somehow, you’re back to single digits before the month even ends. Bills show up like uninvited guests. Groceries cost more than they did last month. And that “emergency fund” you keep meaning to build? It’s still a distant dream, not a reality.
Sound familiar? You’re not alone. Millions of people are stuck in the same exhausting cycle working hard, yet watching money evaporate faster than they can earn it.
Here’s the thing that frustrates me most: it’s not that you’re bad with money. Nobody taught you the real strategies to keep it. Most advice out there is either painfully obvious (“just spend less!”) or completely unrealistic (“stop buying coffee!”).
But what if the problem isn’t your willpower? What if it’s your approach?
You don’t need a finance degree or a six-figure salary to turn things around. You just need a clear, practical roadmap designed for regular people trying to get ahead. Whether you’re saving for an emergency, a vacation, or just want to stop living paycheck to paycheck, the best ways to save money fast start with changing how you think about everyday spending.
Over the next few minutes, I’ll walk you through simple, no-fluff steps that actually fit into your real life. No judgment, no complicated spreadsheets, no crazy sacrifices. Just honest advice from someone who’s been there.
Ready? Let’s dive in and plug those money leaks once and for all.
What Is Saving Money, Really?
Let’s clear up a major misconception right away: saving money is not about being cheap. It’s not about eating instant noodles every night or saying no to every social invitation. That’s a myth, and honestly, it’s why most people give up before they even start.
So what is it, then?
At its simplest, saving money means spending less than you earn and keeping the difference for your future self. That’s it. No fancy definitions, no economics degree required.
Think of it like filling a bucket with water. If the bucket has holes your expenses you need either a stronger flow of water (more income) or smaller holes (less spending). Both work, but one is easier to control in the short term.
Let me give you a real-world example to make this click.
Imagine you bring home $4,000 a month after taxes. Your rent, utilities, groceries, transportation, and minimum debt payments total $3,500. That leaves you with $500 of breathing room.
Now, here’s where most people go wrong. They spend that entire $500 on takeout, movies, random Amazon finds, and a few “treat yourself” purchases. Before they know it, the money is gone, and they have nothing to show for it.
But if you consciously decide to transfer $200 of that into a separate savings account and live on the remaining $300 for fun stuff? Congratulations you just saved $200. Simple as that.
Saving is a conscious choice. It’s paying your future self before your present impulses.
Here’s another thing beginners often get wrong. They think saving only counts if it’s for a big goal a vacation, a house, a new car. Those are great, but saving also covers the boring, unglamorous stuff. Car repairs. Medical bills. The week your hours get cut at work. That’s your safety net, your breathing room, your escape hatch from paycheck-to-paycheck stress.
And here’s the secret nobody tells you: you don’t need to save a lot to start. Even $20 a week adds up to over $1,000 in a year. The habit is what matters, not the amount.
Forget the complicated theories. Saving is simply making sure future you has options. Now let’s get into why this is so damn hard for most people.
Why Most People Struggle to Save Money
Before we talk solutions, we need to address the elephant in the room. Why is saving so ridiculously difficult?
It’s not because you’re lazy or irresponsible. It’s because the system is literally designed to make you spend, and your brain isn’t wired to resist it. Let’s break down the real reasons your bank account stays stuck.
Lifestyle Creep: The Raise That Disappears
You finally get a raise. Maybe it’s $300 more a month. Awesome, right?
But somehow, by the end of the month, you’re still broke. How does that happen?
That’s lifestyle creep. As your income goes up, your spending rises right alongside it often before you even notice. You upgrade your internet plan. You add a premium streaming service. You order takeout twice more per week. You grab a fancier coffee every morning.
By the time you do the math, that extra $300 is completely gone. And what do you have to show for it? Faster Wi-Fi and a few extra pounds.
Why this matters: Lifestyle creep is sneaky. It feels like normal life improvements, not overspending. But it steals your savings potential without you ever making a conscious bad decision.
The fix: Route new income to savings before you get used to having it. The day your raise hits, increase your automatic savings transfer.
The “It’s Just a Small Purchase” Trap
Four bucks for coffee. Fifteen for lunch. Twelve for that app subscription you forgot about.
Individually, these feel harmless. A little treat. No big deal.
But collectively? They form a black hole in your budget. Behavioral economists call this “painless spending” because the amount is so small it doesn’t trigger your mental alarm bells.
Take Maria. She buys a $6 sandwich and a $3 drink every workday. That’s $45 a week, $180 a month, and over $2,000 a year.
If you’d asked Maria to save $2,000, she’d tell you it was impossible. But she was spending that much without even realizing it.
Why this matters: These micro-expenses are the silent killers of savings plans. They don’t hurt in the moment, so you never notice them. But over months and years, they steal thousands from your future.
The “Out of Sight, Out of Mind” Effect
Here’s something that trips up even financially savvy people: subscriptions and automatic payments you completely forget about.
That gym membership you haven’t used since January? Still charging you $50 a month. That streaming service you signed up for to watch one show? Still billing you a year later.
These aren’t small amounts either. They quietly drain hundreds from your account annually without you ever noticing.
Why this matters: These forgotten expenses are pure waste. You’re paying for things you don’t use literally throwing money away.
The fix: Scroll through your bank statements line by line at least once every three months. You’ll almost always find at least one charge that makes you say, “Oh yeah, I need to cancel that.”
Real example: Mike discovered he’d been paying $15/month for cloud storage he stopped using when he switched phones. That was $180 a year for absolutely nothing. He canceled it in two minutes.
Social Pressure and the Comparison Trap
You see friends dining at nice restaurants. Posting vacation photos. Showing off new purchases on social media.
Suddenly, your normal life feels inadequate. So you spend to keep up even if it means stretching your budget.
This isn’t weakness; it’s basic human psychology. We’re wired to compare ourselves to others. But here’s what those posts don’t show: credit card debt, money borrowed from family, or the fact that they’re saving nothing for emergencies.
Why this matters: Spending to impress people who aren’t paying your bills is one of the fastest ways to stay broke. That $80 dinner you can’t afford? It doesn’t make you richer, happier, or more respected. It just makes your bank account smaller.
Real example: Lisa felt pressure to join every office happy hour and bridal party. She was spending over $200 a month on social obligations she didn’t even enjoy. When she started saying “no” more often or suggesting cheaper alternatives she saved $2,400 in a year without losing any friendships.
Lack of a Specific Goal
“Saving money” is too vague. It’s like saying “I want to get fit.” Without a clear target, you have no motivation and no way to measure progress. You save aimlessly for a while, get bored, and quit.
Why this matters: Your brain needs a reason to delay gratification. When you have a specific, tangible goal $1,000 emergency fund, $500 for a new laptop, $3,000 for a trip saving becomes exciting. Every dollar you set aside is a step closer to something real.
Real example: Instead of saying “I need to save more,” David set a goal of $2,000 for a used motorcycle. He printed a visual tracker for his fridge and colored in a block for every $50 saved. Nine months later, he bought the bike. The goal made the sacrifice feel worthwhile.
Best Ways to Save Money Fast
Alright, enough about problems. Let’s get into solutions.
You don’t need to overhaul your entire life to start seeing results. These are the tactics that actually move the needle not the fluffy advice you read on generic finance blogs. Pick two or three that feel doable, start today, and watch your balance grow.
1. The 24-Hour Rule for Impulse Buys
Here’s the thing about most purchases: they aren’t urgent. That “must-have” jacket or gadget is usually driven by emotion excitement, boredom, or stress.
The 24-hour rule is simple. Force a pause. Wait one full day before buying any non-essential item over $30.
Nine times out of ten, you’ll come back the next day and realize you don’t actually want or need the item. The emotional rush fades, and logic takes over.
Example: You’re scrolling online and see a $120 pair of sneakers on sale. Instead of clicking “Buy Now,” add them to your cart and close the tab. Wait 24 hours. When you come back, ask yourself: *Would I rather have these shoes or $120 in my savings account?* Most people choose the cash.
Common mistake: Don’t use the 24 hours to justify the purchase. “I work hard, I deserve this” is a trap. Stick to the rule strictly.
2. Automate Your Savings Before You See It
Let’s be honest: willpower is finite. If you rely on remembering to save at the end of the month, you’ll almost always fail because there’s “nothing left.”
Automation removes your brain from the equation. When money moves to savings the same day you get paid, you psychologically adjust to living on the new, smaller amount.
Example: Set up a recurring transfer of $50 or $100 from your checking to your savings account for the day after each paycheck. If you get paid bi-weekly, that’s up to $2,600 a year saved without lifting a finger. If your employer offers direct deposit, split your paycheck directly into two accounts so you never even see the money.
Common mistake: Don’t automate into an account that’s too easy to transfer back from. Use a separate bank that takes 1-2 business days to transfer, making it harder to impulse-withdraw.
3. The “No-Spend” Challenge Week
This is like a financial detox. For seven days, you only spend money on absolute necessities: rent, utilities, groceries, transportation to work, and debt payments.
Absolutely nothing else. No coffee shops. No takeout. No movies. No online shopping. No convenience store snacks.
Example: Most people save $50-$150 in that single week. Even if you only do this once a quarter, you’ll bank $200-$600 a year with zero long-term sacrifice.
Common mistake: Don’t stock up before the challenge. That defeats the purpose. Start on a Monday with exactly what you already have at home. Use it up, get creative, and see how little you truly need.
4. The 30-Day Rule for Big Purchases
The 24-hour rule works for small impulse buys. But for anything over $100, give yourself a full 30 days.
Write down what you want, the price, and the date. Put it somewhere you’ll see it. If you still want it after 30 days, and you have the cash set aside, go ahead and buy it.
Why it works: Most big purchases are driven by novelty and excitement. That feeling fades within a week or two. By waiting a month, you separate genuine need from temporary desire.
Example: Jenna wanted a $250 air fryer she saw in a social media ad. She put it on her “30-day list.” Two weeks later, she realized she already had a perfectly good oven and had only cooked frozen fries twice in the past year. She skipped the purchase and used the money for a weekend getaway instead.
Common mistake: Don’t use the 30 days to obsess over the item or find reasons to justify it. Put it on the list and move on. If it’s truly important, you’ll remember it naturally.
5. The “One In, One Out” Rule
For every new non-essential item you bring into your home, you must sell, donate, or throw away something of similar value.
This isn’t just about decluttering it’s about curbing unnecessary spending.
Why it works: It forces you to consider the true cost of a purchase. That new jacket? You’ll need to give up an old one. That new gadget? Something else has to go. This extra friction makes you pause and think twice.
Example: Mark wanted new headphones for $150. But the “one in, one out” rule meant he had to sell his old ones first. He listed them online, they sold for $60, and suddenly the new ones only cost him $90 out of pocket. He saved money and cleared clutter at the same time.
Common mistake: Don’t apply this to essentials like groceries or toiletries. This rule is for discretionary items only clothes, electronics, home decor, hobby supplies.
6. The Envelope System for Variable Expenses
Here’s an old-school trick that still works brilliantly. Withdraw cash for categories where you tend to overspend groceries, dining out, entertainment and put each category’s budget in a labeled envelope.
When the envelope is empty, you’re done spending for the week.
Why it works: Cash is tangible. Watching a physical stack of money shrink hurts more than swiping a card. You naturally become more mindful because you can see your budget depleting in real time.
Example: Rachel allocated $80 per week for groceries and $40 for dining out. By Thursday, she’d often have only $15 left in her grocery envelope. That Friday, instead of buying extra snacks and fancy ingredients, she made do with what she already had. She saved about $120 a month using this system.
Common mistake: Don’t “borrow” from one envelope to cover another. If you run out of dining money, that’s it cook at home. The rules are what make this work.
7. Challenge Yourself to a “Spending Freeze”
Pick three consecutive days each month say the 1st, 2nd, and 3rd and spend absolutely nothing. No coffee runs, no takeout, no Amazon orders, no impulse snacks at the gas station.
Just essentials like rent, utilities, and transportation to work.
Why it works: It’s short enough to be painless but frequent enough to make a difference. Over a year, that’s 36 days of zero discretionary spending.
Example: Carlos committed to three no-spend days per month. He’d pack lunch, brew coffee at home, and entertain himself with free activities. After six months, he’d saved over $500 without really feeling deprived it was just three days a month.
Common mistake: Don’t “spend ahead” by buying extra stuff the day before a freeze. That defeats the purpose.
8. Use the 24-Hour Price Comparison Rule
Before making any purchase over $50, spend 10 minutes checking at least two other retailers.
This isn’t about obsessively hunting for coupons it’s about preventing overpaying out of convenience or laziness.
Why it works: Retailers count on impulse and convenience. Same product, different price, wildly different savings. Often, the difference is as simple as buying online instead of in-store.
Example: Tom needed a new blender. At the local store, it was $120. He checked online, found the exact same model at another retailer for $95, and they price-matched. He saved $25 in under five minutes.
Common mistake: Don’t get sucked into “saving” money by buying something you didn’t need because it was on sale. Price comparison is only valuable for items you were already going to buy.
9. The Pay-Yourself-First Method
Treat your savings like a bill that must be paid and pay it first, not last. The day you get paid, immediately transfer your savings target into a separate account. What’s left is what you have to live on.
Why it works: It flips the psychology. Most people pay everyone else first landlord, utilities, credit cards, grocery store and save whatever is left over. Which is usually nothing. Paying yourself first ensures you’re prioritized.
Example: Dana earns $3,200 a month. She set up an automatic transfer of $320 on payday 10% of her income. She never sees that money, so she doesn’t miss it. After a year, she had $3,840 without ever making a conscious “savings decision.”
Common mistake: Don’t set the amount too high. Start with 5-10% and increase gradually. If you set it too high and can’t cover your bills, you’ll just transfer it back and abandon the habit.
10. Review Every Recurring Bill Annually
Insurance, internet, phone plans, and streaming services often increase rates quietly each year. Most people never notice because the changes are small $2 here, $5 there. But those add up to $100-$300 annually without any benefit to you.
Why it works: Companies rely on your inertia to overcharge you. By reviewing bills annually, you catch sneaky increases and either negotiate better rates or switch providers. This is pure savings with zero lifestyle sacrifice.
Example: Maria reviewed her car insurance and realized she’d been paying $85/month for three years. She shopped around, found a better policy for $62/month with the same coverage, and saved $276 that year with one afternoon of effort.
Common mistake: Don’t just accept “loyalty discounts” at face value. New customer deals are often cheaper than loyalty pricing. Call and ask for a better rate sometimes that’s all it takes.
Expert Tips: What The Gurus Don’t Tell You
You’ve read the basic advice a hundred times. Cut coffee. Pack lunch. Skip Netflix. And yet, you’re still struggling. That’s because the standard tips only scratch the surface.
After years of helping people fix their finances, here are the five unconventional strategies that actually work when you’re trying to save fast.
1. Cancel Your Subscriptions But Do It Differently
Everyone tells you to cancel subscriptions. And most people try they scroll through their bank statement, spot a few they don’t use, and hit cancel. Then, three months later, they’ve signed up for new ones. The cycle repeats.
The pro approach: Instead of canceling everything, do a “subscription audit” with a twist. For each service, calculate the annual cost, not the monthly. That $15/month streaming service is $180 a year. That $10/month fitness app is $120. Once you see the yearly total, ask yourself: Is this worth a weekend getaway?
Real-world example: Sarah did this and realized her four streaming services cost her $600 annually. She kept one, rotated the others based on what she wanted to watch, and saved over $400 in a year without feeling deprived.
Where people fail: They cancel the wrong things. They ditch Netflix but keep the gym membership they never use, or the meal kit box that costs triple what groceries would. Focus on cost-per-use, not just the monthly number.
2. The 5% Negotiation Rule
Here’s something most people never try: negotiate your bills. Not just your salary your internet bill, phone plan, gym membership, even your rent. Companies expect you to ask. They build wiggle room into every price.
The pro approach: Call your service providers once a year and say, “I’m considering switching providers because your competitor is offering X price. Can you match that or offer a better deal?” You’d be shocked how often they’ll lower your rate just to keep you.
Real-world example: Tom called his internet provider and said, “I’ve been a customer for three years and saw a new customer deal for $20/month less. Can I get that rate?” They said yes in two minutes. He saved $240 that year with one short phone call.
Where people fail: They assume prices are fixed. They’re not. The price you pay is the price you accept. Companies count on your discomfort with negotiating. Don’t be shy the worst they can say is no.
3. The “30-Day Pause” Before Any Subscription Renewal
Annual subscriptions are sneaky. They auto-renew, and most people don’t notice until the charge hits. Then they say, “Oh well, might as well keep it.”
The pro approach: Put a calendar reminder for 30 days before each annual renewal. When it pops up, ask yourself: Did I use this enough to justify another year? If the answer is even slightly “no,” cancel immediately.
Real-world example: Lisa had a $99/year fitness app that auto-renewed for three years. She used it maybe twice. When she finally set a reminder and cancelled, she’d wasted nearly $300. Now she reviews every annual subscription a month before renewal.
Where people fail: They wait until after the renewal hits, then it feels like too much effort to cancel and get a refund. The 30-day reminder gives you space to decide before money leaves your account.
4. The Shared Expense Audit
Couples, roommates, and friends often split expenses unevenly without realizing it. One person pays more for utilities, another covers more groceries, and over time, the imbalance adds up.
The pro approach: Every three months, sit down and list all shared expenses for the period. Total each person’s contribution. If there’s more than a $50 difference, settle up. It’s not about being petty it’s about fairness.
Real-world example: John and his roommate shared groceries and utilities. John was paying $80 more per month because he did the grocery shopping and his roommate reimbursed him late or not at all. When they started tracking properly, they split everything fairly and John saved nearly $1,000 that year.
Where people fail: They let small imbalances slide until they become big ones. Then resentment builds, and the conversation becomes awkward. Regular, small audits prevent awkwardness and save money.
5. The “Sleep on It” Rule for Online Carts
This sounds obvious, but here’s the pro version: leave items in your online cart for 24 hours, but also leave the website. No browsing, no checking back. Close the tab completely.
Why it works: Online retailers use urgency tactics “only 2 left!” to push you into buying. Removing yourself from that environment lets the urgency fade. Often, you’ll return the next day and realize you didn’t want the item that badly.
Real-world example: Sarah filled a $300 shopping cart at an online clothing store. She closed the tab and went to bed. The next day, she reopened it, looked at each item, and realized she only actually wanted two things. She bought those for $80 and saved $220.
Where people fail: They keep returning to the cart throughout the day, looking at the items, justifying the purchase. That defeats the purpose. The rule is close and don’t look back until tomorrow.
Pros and Cons of Saving Money
Let’s be real saving money isn’t all rainbows and security, just like it isn’t all sacrifice and misery. Like anything in life, it comes with trade-offs. Here’s an honest look at both sides so you can decide what balance works for you.
Pros of Saving Money
Financial Security and Peace of Mind
Having money set aside means life’s unexpected punches car breakdowns, medical bills, or job loss don’t become emergencies. Instead of panic, you feel a quiet confidence. That peace of mind alone is worth more than most things you could buy.
Freedom and Options
Savings give you choices. Want to quit a toxic job? You can. Want to start a side business? You have seed money. Want to take a career break? Go for it. Money in the bank is literally options in your pocket.
Reduced Stress and Better Sleep
Financial stress is one of the leading causes of anxiety and relationship strain. Even a modest emergency fund removes that constant low-level dread. You stop waking up at 3 AM doing mental math about bills.
Compound Growth Over Time
Money saved today grows. Whether it’s in a high-yield savings account or invested, your money works for you while you sleep. The earlier you start, the more powerful this effect becomes.
Ability to Afford Bigger Goals
Want a home, a vacation, or a new car? Those aren’t possible without saving first. Small, consistent savings turn into down payments and dream trips that would be impossible on a single paycheck.
Cons of Saving Money
Opportunity Cost
Every dollar you save is a dollar you’re not spending on something else. That might mean skipping a vacation, eating out less, or delaying a purchase you really want. Saving forces trade-offs, and sometimes those trade-offs sting.
It Can Feel Restrictive
If you take it too far, saving can make life feel small. Saying “no” to every social outing, every treat, and every little joy can lead to burnout and resentment. Balance matters saving shouldn’t make you miserable.
Inflation Eats Away at Cash
Money sitting in a regular savings account loses purchasing power over time. If inflation is 3% and your account earns 1%, you’re effectively losing 2% each year. That’s why experts recommend investing some savings for long-term growth.
Takes Time to See Results
Saving isn’t instant gratification. You might squirrel away $50 a week and feel like you’re getting nowhere for months. That slow pace can be discouraging, and many people give up before they see meaningful progress.
Can Become an Obsession
For some, saving turns into hoarding. They become so afraid of spending that they deny themselves basic comforts and experiences. Money becomes a goal in itself, rather than a tool for a better life. That’s not wealth that’s anxiety with a bank balance.
The Bottom Line
Saving money is undeniably beneficial, but it’s not without its downsides. The key isn’t to save every single penny or to spend without thought. It’s about finding your personal balance enough saved to feel secure, but enough spent to actually enjoy your life along the way.
Frequently Asked Questions About Saving Money
How much money should I have in my emergency fund?
Most experts recommend three to six months’ worth of essential expenses. That means rent, utilities, groceries, transportation, and minimum debt payments not your Netflix subscription or takeout budget. If you’re self-employed or have an unstable income, lean toward six months. Start with a smaller goal of $1,000 first, then build up gradually. Even one month’s worth puts you ahead of most people.
Can I save money on a low income?
Absolutely. Saving isn’t about the amount it’s about the habit. Even $5 or $10 per paycheck adds up over time. Focus on cutting one small expense consistently, like bringing lunch twice a week or canceling one unused subscription. The percentage doesn’t matter; what matters is starting. Once the habit sticks, you’ll naturally find more ways to save as your income grows.
What’s the 50/30/20 budget rule?
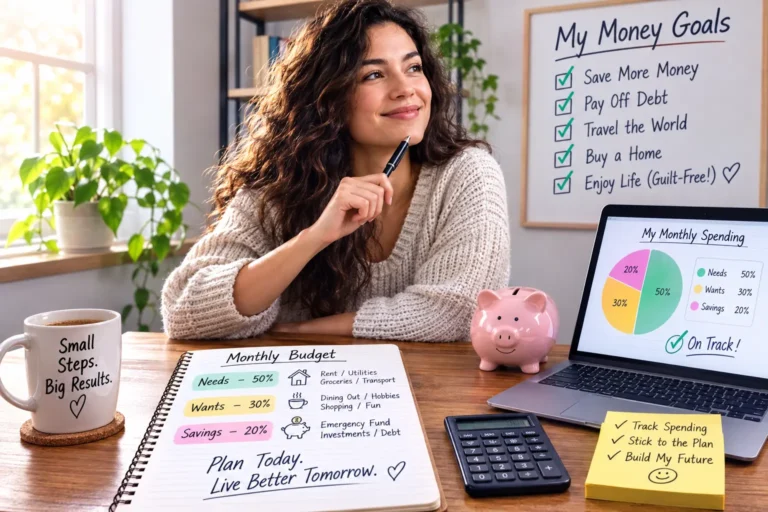
It’s a simple budgeting framework where you allocate 50% of your after-tax income to needs (rent, groceries, utilities), 30% to wants (dining out, entertainment, shopping), and 20% to savings and debt repayment. It’s beginner-friendly because it doesn’t require tracking every single penny. Adjust the percentages based on your situation if rent is high, you might do 60/20/20 instead.
Should I save or pay off debt first?
It depends on the interest rate. If your debt has high interest (above 10%, like credit cards), focus on paying that down first while saving a small starter emergency fund of $500-$1,000. If your debt has low interest (like a student loan under 5%), prioritize saving and investing while making minimum payments. The math says pay high-interest debt first, but having some cash buffer prevents you from using more credit when emergencies hit.
How can I save money on groceries without couponing?
Shop with a list and stick to it. Plan meals around what’s on sale that week. Buy store brands instead of name brands they’re often identical. Shop the perimeter of the store where whole foods live, and avoid the middle aisles packed with processed items. Also, never shop hungry. Studies show you spend significantly more when your stomach is empty. These simple habits beat couponing any day.
What’s the best way to save for a vacation?
Open a separate savings account just for travel. Set up an automatic transfer of a set amount each payday even $20 adds up to $520 a year. Also, round up your purchases to the nearest dollar using a “round-up” app and transfer the difference to your vacation fund. You’ll be surprised how fast micro-savings accumulate without feeling painful.
Is it okay to dip into savings for non-emergencies?
Technically, yes it’s your money. But you should have a system. Before withdrawing, ask yourself: Is this expense urgent, important, or just convenient? If it’s the last one, pause and reconsider. Many people break their savings habit by justifying non-emergencies. If you must withdraw, replenish it within 30 days to stay on track.
How do I save when my income is irregular?
This is tough, and you have my sympathy. The secret is the “percentage method.” On the day you receive a payment, immediately set aside a fixed percentage say 15-20% into savings. What’s left is what you live on. This way, smaller checks mean smaller savings, but you always save something and keep the habit alive.
Can I save money by switching banks?
Sometimes. Look for banks with no monthly fees, free ATM access, and higher interest rates on savings. Online banks often offer 4-5% APY compared to traditional banks’ 0.01%. Switching could earn you $100-$200 extra annually just in interest. That’s free money for a one-hour task. Just check for minimum balance requirements before moving.
How do I track my savings progress without feeling overwhelmed?
Keep it stupid simple. Check your savings balance once a month on the same day, like the first of the month. Write it down. Celebrate even small increases. Don’t check daily; that creates anxiety and encourages bad decisions. The goal is steady progress, not daily monitoring.
Why do I save money but still feel broke?
This is a mindset issue, not a math issue. If you’re saving but feel broke, you’re likely setting your savings target too high or tracking every dollar too rigidly. Give yourself a reasonable fun-money budget each month even $50 and spend it guilt-free. Saving shouldn’t feel like punishment. Remember, you’re building a better future, not living in financial prison.
Conclusion: Your Journey Starts Today
Let’s pause for a moment.
You came here looking for the best ways to save money fast, and you’ve now got a toolbox packed with strategies. But here’s the truth most articles won’t tell you: you don’t need to do all of them.
Pick two. Maybe three. That’s enough.
Start with the 24-hour rule for impulse buys. Set up an automatic transfer of $25 per paycheck. Try a no-spend weekend instead of a full week. Small wins build momentum, and momentum builds real change.
Remember, saving money isn’t about becoming a miser or saying no to everything fun. It’s about making conscious choices so your money serves you not the other way around. It’s about buying yourself peace of mind, freedom, and options. That’s worth more than any gadget or takeout meal.
The hardest part is always the first step. So here’s your challenge: do one thing today. Not tomorrow. Not Monday. Today.
Open your banking app and move $10 to savings. Cancel that subscription you forgot about. Write down one expense you can cut this week.
Future you is counting on present you. And honestly? Future you will be so grateful you started.