How to Start Budgeting Effectively: A Beginner’s No-Nonsense Guide
Introduction: Start With the “Why,” Not the Spreadsheet
When most people hear the word budget, they imagine complicated spreadsheets, shrinking bank balances, and a long list of things they are no longer allowed to buy. Maybe you picture giving up your morning coffee, avoiding restaurants, or constantly checking whether you have enough money left until payday.
But budgeting isn’t supposed to feel like financial punishment.
At its heart, budgeting is about clarity and control. It gives you a clear picture of where your money is going and helps you decide whether your spending actually supports the life you want.
If you’ve ever opened your banking app near the end of the month and wondered, “Where did all my money go?”, you’re certainly not alone. The problem isn’t necessarily that you’re irresponsible with money. More often, there’s simply no reliable system behind your spending.
Instead of making financial decisions based on guesswork, budgeting gives your money a purpose.
Learning how to start budgeting effectively doesn’t require advanced math skills or an extremely restrictive lifestyle. It means creating a simple system that allows you to pay your bills, save for the future, enjoy your money, and avoid that end-of-month panic.
Before choosing a spreadsheet or downloading an app, though, there’s one thing worth fixing first: your mindset. A fancy budgeting tool won’t help much if your approach to money remains the same.
What Is Budgeting, Really?
Let’s clear up one common misconception: budgeting isn’t a financial prison.
It’s not a punishment for spending money, and it isn’t something reserved for people with low incomes or serious debt.
Simply put, a budget is a plan for your money. Instead of spending first and wondering where everything went afterward, you decide ahead of time how you want to use your income.
Think of it as a GPS for your finances.
When you’re driving somewhere unfamiliar, a GPS gives you a route. If you make a wrong turn, it doesn’t tell you to abandon the journey. It simply recalculates.
Your budget should work the same way. You don’t have to follow it perfectly every day. You just need a plan that helps you get back on track when something changes.
A Simple Example
Imagine you bring home $2,000 at the beginning of the month.
Without a budget, you might pay $1,000 in rent, buy groceries, order takeout, fill your car with gas, purchase something on sale, and handle a few other expenses. By the 25th, perhaps only $50 remains.
Now consider the same $2,000 with a plan:
- Rent: $1,000
- Groceries: $300
- Gas: $150
- Eating out: $100
- Emergency savings: $100
The important difference isn’t necessarily how much you spend. It’s that you decided where the money would go before it disappeared.
That’s the real purpose of budgeting. You’re not necessarily trying to spend less on everything. You’re trying to make sure your money goes toward the things that matter most.
Why Do People Start Budgeting?
People rarely decide to budget for no reason.
Usually, something happens that makes them realize their current approach isn’t working. Maybe they constantly run out of money, have an important savings goal, or experience a major life change.
Understanding your motivation can make it easier to stick with budgeting when the habit still feels unfamiliar.
Here are three common reasons people finally create a budget.
1. The “Where Did My Money Go?” Problem
This is probably the most familiar situation.
You receive your paycheck, pay a few bills, live normally, and suddenly you’re checking your bank balance several days before payday.
You might start calculating what you can afford at the grocery store or hesitate before filling your gas tank. The frustrating part is that you don’t necessarily remember making any major purchases.
The real problem is often lack of awareness, rather than reckless spending.
Example: Sarah earns $4,200 each month. After paying rent, utilities, groceries, and her car payment, she is surprised to discover that only $80 remains near the end of the month.
She starts tracking her purchases and discovers that coffee, lunches, snacks, and small convenience purchases have been costing her more than $500 every month.
She wasn’t buying luxury items. She simply wasn’t seeing the pattern.
2. The “I’m Saving for Something” Motivation
Budgeting isn’t always about fixing a financial problem.
Sometimes you’re budgeting because there’s something you genuinely want.
Perhaps you’re saving for a vacation, a house deposit, a new vehicle, education, or simply greater financial freedom.
That can be a much more positive reason to budget because you’re connecting today’s decisions with something you care about.
Example: Marcus wants to take his family to Disney World in 18 months. He expects the trip to cost around $6,000, so he needs to save approximately $333 each month.
After reviewing his spending, he finds $200 he can redirect from restaurants and subscriptions. He then earns the remaining $133 through a small side gig.
He’s not simply “cutting spending.” He’s turning his monthly budget into a way of purchasing a future experience.
3. A Major Life Change
Life can force you to rethink your finances.
Marriage, having a child, buying a home, losing a job, receiving an inheritance, or starting a business can completely change your income and expenses.
The old habit of simply “winging it” may suddenly stop working.
A budget becomes useful because it gives you a framework for navigating the new financial reality.
Best Ways to Start Budgeting Effectively
Once you understand why budgeting matters, it’s time to build a system you can actually live with.
The best budget isn’t the most complicated one. It’s the one you can maintain consistently.
Tip 1: Track Your Spending for Seven Days Without Changing Anything
This may sound strange, but don’t immediately try to fix your spending.
For the first seven days, simply observe it.
Buy your normal coffee. Order your usual takeout. Make the purchases you normally make. Just record every expense.
You can use:
- A notes app
- A notebook
- A spreadsheet
- Your banking app
- A budgeting app
The objective isn’t to judge yourself. It’s to collect information.
Why This Helps
You can’t make meaningful changes if you don’t know what you’re actually doing.
A week of honest tracking gives you real data rather than an idealized version of your spending habits.
Common Mistake
Don’t suddenly become extremely frugal because you’re tracking your expenses.
If you normally spend $80 on takeout, record the $80. That’s your baseline. You can decide what to change after you understand your habits.
Tip 2: Figure Out Your Real Monthly Income
Your budget should be based on the money that actually reaches your bank account, not your salary before deductions.
For salaried workers, use your take-home pay after taxes and other deductions.
For freelancers, hourly workers, or anyone with unpredictable income, planning requires more caution.
One conservative approach is to review your recent income and use a lower month as your budgeting baseline. For example, if your income has ranged from $2,800 to $4,200, building your essential budget around $2,800 provides more breathing room.
When you earn more than your baseline, the extra money can go toward savings, debt, or other financial goals.
Common Mistake
Don’t budget using gross income.
If taxes and other deductions are removed before your paycheck arrives, that money isn’t available for everyday spending.
Tip 3: Try the 50/30/20 Rule
If creating dozens of categories feels overwhelming, start with something simple.
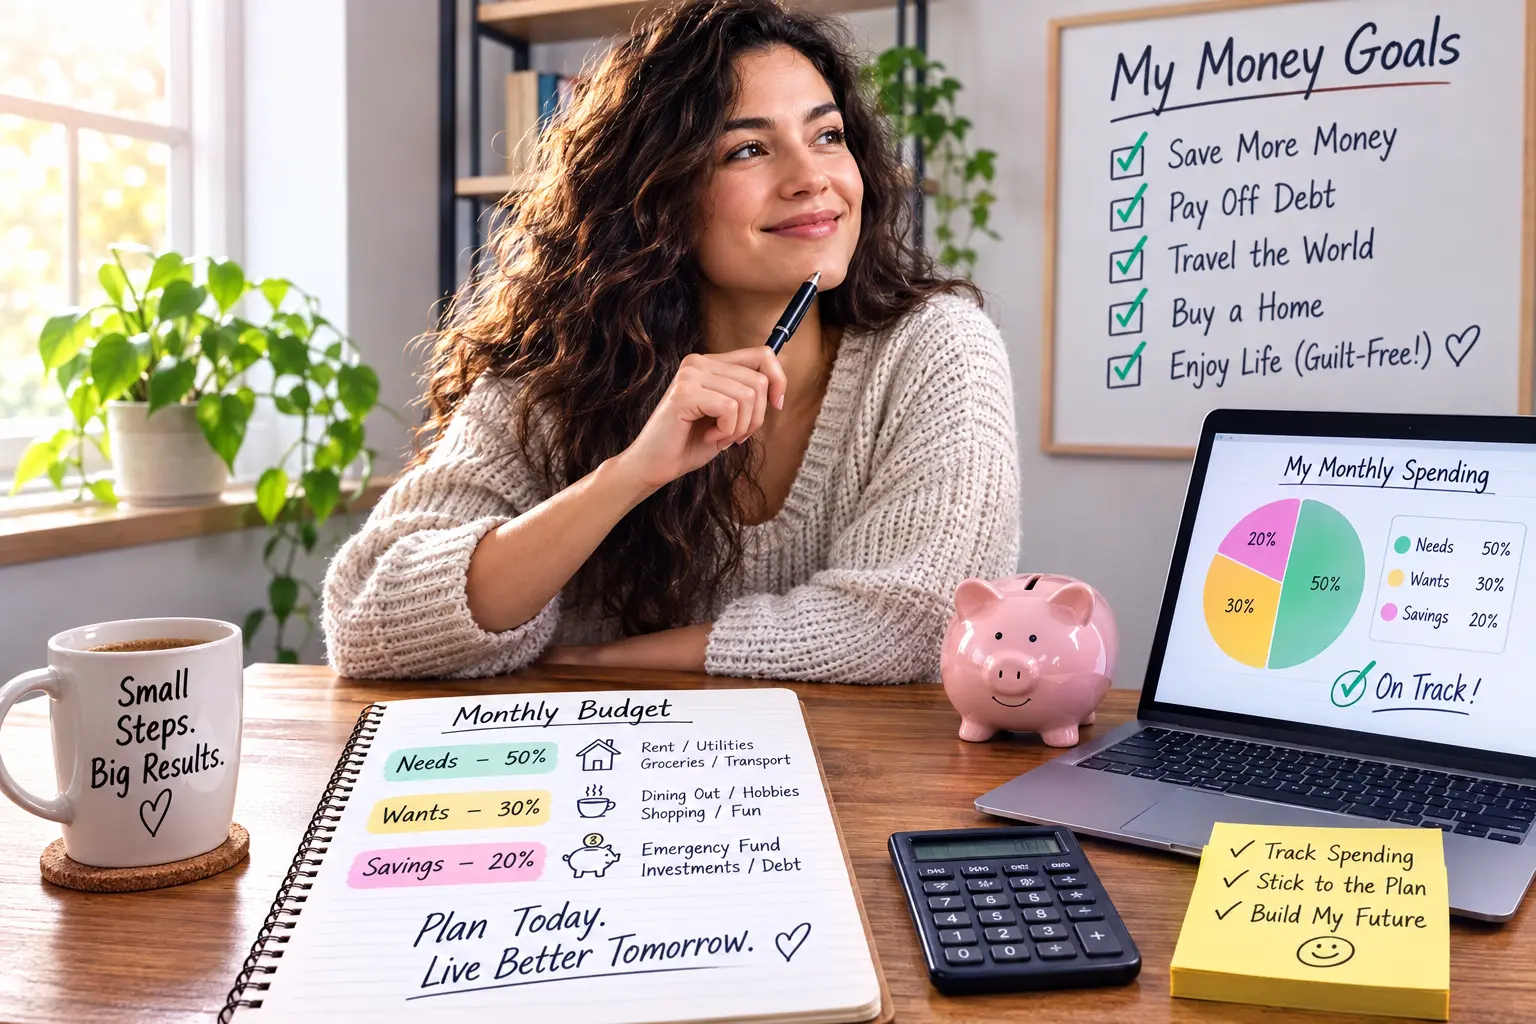
The 50/30/20 rule divides take-home income into three broad groups:
- 50% for Needs: Housing, utilities, groceries, insurance, transportation, and minimum debt payments.
- 30% for Wants: Restaurants, entertainment, hobbies, subscriptions, shopping, and vacations.
- 20% for Savings and Debt: Emergency savings, investments, retirement contributions, and additional debt payments.
For example, if you bring home $3,000 per month:
- Needs: $1,500
- Wants: $900
- Savings/debt: $600
This isn’t a law you must follow perfectly. It’s a starting framework that makes budgeting easier.
Why It Works
One of the biggest advantages is that it deliberately leaves room for enjoyment.
You’re not telling yourself that you can never eat at a restaurant or buy something fun. You’re simply giving those expenses a defined place in your budget.
Common Mistake
Be honest when deciding whether something is a need or a want.
A new smartphone may be useful, but that doesn’t automatically make it an essential expense. Similarly, a daily specialty coffee is usually a want rather than a necessity.
Tip 4: Pay Yourself First
One of the easiest ways to build savings is to automate them.
Instead of waiting until the end of the month to see what’s left, move money into savings as soon as your paycheck arrives.
You can schedule an automatic transfer from your checking account to a separate savings account on payday.
Even $25 per paycheck is a legitimate starting point.
Why Automation Works
Relying entirely on willpower is difficult.
If savings depend on whatever happens to remain at the end of the month, you may find that there’s never much left.
Automation turns saving into a routine rather than a repeated decision.
Common Mistake
Don’t assume you need to save a huge amount immediately.
Saving $25 is better than saving nothing. At $25 per paycheck, depending on your pay schedule, you’re already building a meaningful annual habit.
The amount can increase as your financial situation improves.
Tip 5: Use Cash Envelopes for Problem Categories
Some spending categories are simply harder to control than others.
Groceries, restaurants, entertainment, and shopping can easily expand when you aren’t paying close attention.
A cash-envelope system can create a physical limit.
For example, if you decide to spend $300 on groceries for the month, you can set aside that amount in cash. Once it’s gone, you know you’ve reached your planned limit.
You can use the same approach for restaurants or entertainment.
Why It Can Work
Physical cash creates a stronger psychological connection to spending than simply tapping a card.
That extra awareness can make it easier to pause before making an unnecessary purchase.
Common Mistake
Don’t turn your entire financial life into an envelope system.
Fixed expenses such as rent, utilities, and other recurring bills can remain automated. Use cash mainly for the categories where you repeatedly overspend.
Tip 6: Do a Five-Minute Weekly Budget Check
You don’t need to stare at your finances every day.
But waiting until the end of the month isn’t ideal either.
Set aside around five minutes once a week, perhaps every Friday morning, to look at your spending.
Ask yourself:
- How much remains in each category?
- Are any categories running low?
- What expenses are coming up?
- Do I need to move money between categories?
For example, if you have $40 left in your grocery budget but $60 remaining in your restaurant budget, you may decide to shift some money toward groceries.
Why This Works
A budget isn’t a document you create once and forget about.
It’s a living plan.
Weekly check-ins allow you to make small adjustments before a small problem becomes a major one.
Common Mistake
Don’t turn a five-minute check into a stressful hour-long financial investigation.
Keep it short and practical.
Tip 7: Have an Overspending Recovery Plan
Here’s an important truth: you will overspend sometimes.
A birthday dinner might cost more than expected. Your car might need repairs. You could simply have a difficult week and order more takeout than usual.
That doesn’t mean your entire budget has failed.
Instead, make a recovery plan before something goes wrong.
You could:
- Reduce spending in another category.
- Temporarily lower your entertainment budget.
- Earn a little extra income.
- Use available savings if the expense is genuinely necessary.
- Accept the difference and adjust next month’s budget.
The objective isn’t to produce a perfect month.
The objective is to keep going.
Expert Budgeting Tips Most Apps Won’t Teach You
Basic budgeting advice can get you started, but long-term success often comes from small behavioral changes.
Budgeting apps can track numbers. They can’t always change the way you think about those numbers.
Here are some principles that can make budgeting easier to maintain.
Budget for Your Future Self on Payday
A common pattern looks like this:
- Receive your paycheck.
- Pay immediate bills.
- Spend on wants.
- Save whatever remains.
The problem is that there may be very little left to save.
Try reversing the order.
When your paycheck arrives, immediately transfer money toward savings, investments, or additional debt payments. Then use what’s left for your other expenses.
Example
James receives $3,000 at the beginning of the month.
Before handling his other spending, he transfers:
- $300 to savings
- $100 toward investments
He then pays rent and other expenses using the remaining money.
His savings rate has effectively changed because saving is now automatic rather than optional.
This is the basic principle behind paying yourself first: save first, then spend what remains.
Common Budgeting Mistakes to Avoid
Budgeting isn’t difficult because people lack intelligence. It’s difficult because certain approaches are unrealistic.
Avoiding these common mistakes can make the process much more sustainable.
Mistake 1: Setting Extremely Aggressive Goals
You might decide to cut your spending in half overnight.
Maybe you cancel every subscription, stop eating out completely, and eliminate every small pleasure.
That may feel motivating for a few days.
Then reality arrives.
Extreme restrictions can create frustration and eventually lead to overspending because you feel deprived.
A Better Approach
Make smaller changes.
Instead of cutting restaurant spending by 80%, try reducing it by 20%.
Instead of canceling every subscription, remove one or two you rarely use.
A sustainable budget is usually more valuable than an extreme budget you abandon after three weeks.
Mistake 2: Forgetting Irregular Expenses
Monthly expenses are easy to remember.
Irregular expenses are where many budgets get caught off guard.
Examples include:
- Annual subscriptions
- Car insurance
- Holiday gifts
- Property expenses
- School costs
- Vehicle maintenance
Review your previous year’s spending and identify expenses that don’t happen every month.
Then divide annual costs by 12 and save a portion each month.
For example, if car insurance costs $600 annually, setting aside $50 each month creates a fund for that bill.
This is often called a sinking fund.
Mistake 3: Removing All Fun From Your Budget
A budget containing only bills, debt payments, and savings can become exhausting.
If you give yourself no room to enjoy your money, you’re more likely to eventually rebel against the entire system.
Instead, create a guilt-free spending category.
Even $50 per month can give you room to buy something enjoyable without feeling like you’ve ruined your financial plan.
Mistake 4: Treating Budget Categories as Unchangeable
Your budget shouldn’t be a collection of rigid walls.
Real life changes.
Maybe your friends invite you to a birthday dinner. Maybe groceries cost more than expected. Perhaps transportation expenses suddenly increase.
You can move money between categories when necessary.
If dining out costs more than expected, you might reduce entertainment spending to compensate.
As long as your overall spending remains manageable, adjusting categories isn’t failure.
It’s budgeting realistically.
Mistake 5: Leaving Your Partner or Family Out
If multiple people share finances, everyone needs to understand the plan.
Imagine spending hours creating a detailed household budget while your partner doesn’t even know what the categories are.
That can quickly create frustration.
Instead, schedule a short monthly money conversation.
Discuss:
- Shared financial goals
- Upcoming expenses
- Spending categories
- Savings targets
- Areas where adjustments are needed
The goal isn’t to control each other’s spending. It’s to make financial decisions as a team.
Mistake 6: Quitting After a Bad First Month
Your first budget probably won’t be perfect.
You may forget an annual bill. You may underestimate groceries. You might overspend in several categories.
That’s normal.
Instead of saying, “Budgeting doesn’t work for me,” ask what the month taught you.
Your first budget is a learning tool.
Adjust the numbers and try again.
It can take several months to understand your real spending patterns.
Mistake 7: Choosing an Overly Complicated App
More features don’t automatically mean better budgeting.
Some apps offer detailed charts, reports, account integrations, investment tracking, and dozens of categories.
For a beginner, that can be overwhelming.
A basic spreadsheet or notebook may be more useful if it’s something you’ll actually use.
Once you’ve developed the habit, you can experiment with more advanced tools.
The best budgeting tool isn’t necessarily the most powerful one.
It’s the one you can stick with.
Pros and Cons of Budgeting
Budgeting can be extremely useful, but it isn’t a magic solution.
Understanding both the benefits and the challenges can help you approach it realistically.
The Pros
Complete Financial Clarity
You gain a much clearer picture of where your money goes.
Instead of guessing, you can see exactly how much is available for different priorities.
Less Financial Stress
Having a plan can reduce the anxiety that comes from constantly wondering whether you can afford something.
Even when money is tight, knowing your limits can be reassuring.
More Achievable Goals
A large goal can feel impossible when you only think about the final number.
A budget breaks it into smaller monthly actions.
Whether you’re saving for travel, a home, education, or retirement, you can track measurable progress.
Guilt-Free Spending
A budget doesn’t have to eliminate fun.
When you’ve deliberately included money for entertainment or hobbies, you can spend that amount without wondering whether you’ve destroyed your financial plan.
A Healthier Relationship With Money
Over time, budgeting can change money from something mysterious and stressful into something you actively manage.
Your income becomes a tool rather than something that simply disappears.
Greater Financial Security
Consistent saving and debt repayment can eventually create a financial cushion.
That can make unexpected expenses less disruptive.
The Cons
It Takes Time to Set Up
Your first budget requires some work.
You’ll need to review expenses, calculate income, organize categories, and decide on priorities.
It Can Feel Restrictive Initially
Seeing your spending clearly isn’t always comfortable.
You may discover that certain habits cost more than you realized.
It Requires Maintenance
A budget isn’t completely automatic.
You need occasional reviews and adjustments as your income, expenses, and goals change.
It Can Create Relationship Tension
Money can become a source of conflict when people have different priorities or spending habits.
Open communication is important when finances are shared.
Unexpected Expenses Still Happen
Even an excellent budget can’t predict every emergency.
Car repairs, medical expenses, job changes, and other surprises can still disrupt your plan.
Financial Apps Can Become Complicated
Too many tools and categories can make budgeting feel like another job.
Sometimes simpler is better.
The Bottom Line
Budgeting isn’t a magical solution that instantly fixes every financial problem.
It takes patience, consistency, and a willingness to look honestly at your spending.
But the benefits can be substantial.
The key is to avoid making budgeting harder than it needs to be.
Start with a simple system. Track your spending. Use realistic categories. Automate savings when possible. Review your budget regularly, and give yourself room for unexpected expenses and enjoyment.
An imperfect budget that you actually follow is far more useful than a perfect budget that you abandon.
Frequently Asked Questions About Budgeting
Can I Start Budgeting With an Irregular Income?
Yes.
In fact, budgeting can be especially useful when your income changes from month to month.
A conservative approach is to base your essential budget on a lower-income month rather than assuming you’ll always earn your highest amount.
During stronger months, you can direct the additional income toward savings, debt repayment, or a buffer fund.
How Long Does It Take for Budgeting to Become a Habit?
It depends on the individual, but the source material suggests allowing roughly 60 to 90 days for budgeting to begin feeling more natural.
The first month is often the most challenging because you’re collecting information and discovering your actual habits.
By the second and third months, your categories should become clearer and your weekly reviews may start feeling routine.
Give yourself time to adjust.
Should I Use Cash or Credit Cards When Budgeting?
There’s no single answer.
Cash can be useful for categories where you frequently overspend because the physical spending limit is easy to see.
Credit cards can provide convenience, fraud protection, and rewards, but they should only be used responsibly.
A hybrid approach may work well: use cash for difficult variable categories and cards for fixed or online expenses if you can consistently pay the balance in full.
What’s the Best Budgeting App for Beginners?
You don’t necessarily need an app.
A simple spreadsheet or notebook may be enough when you’re getting started.
Popular budgeting tools can provide useful features, but too many options can overwhelm beginners.
Start with the simplest system that helps you consistently track your money. You can upgrade your tools later.
How Much Should I Save Each Month?
A common starting target is 20% of take-home income, based on the 50/30/20 framework.
However, don’t let that percentage discourage you.
If 20% isn’t realistic right now, start smaller.
Even saving 1% is progress if your alternative is saving nothing.
The important part is creating the habit and increasing the amount when your financial situation allows.
Can Budgeting Help Me Pay Off Debt?
Absolutely.
A budget shows how much money you have available after essential expenses.
You can then direct extra money toward debt using a strategy such as:
- Debt snowball: Focus on the smallest balance first.
- Debt avalanche: Focus on the debt with the highest interest rate first.
A clear budget can help you consistently fund whichever strategy you choose.
What If My Partner and I Have Different Spending Habits?
That’s very common.
The answer isn’t necessarily to force one person’s financial style on the other.
Instead, discuss your shared goals and agree on the major household priorities.
It can also help to give each person a reasonable amount of personal spending money that they can use without having to justify every purchase.
Regular money conversations can prevent disagreements from building up.
How Often Should I Update My Budget?
A full budget review once a month is useful.
You should also consider doing a quick weekly check-in of around five minutes.
The monthly review allows you to plan ahead, while the weekly check helps you catch problems before they become difficult to fix.
Is Budgeting Only for People With Low Incomes?
Not at all.
Budgeting can benefit people at almost any income level.
Someone earning a high salary can still spend everything they earn through lifestyle inflation.
A budget helps ensure that your income is being directed toward your priorities, regardless of how much you make.
What Should I Do If My Budget Doesn’t Work After One Month?
Don’t give up.
Your first budget is a starting point, not a final product.
Look at what went wrong.
Maybe your grocery estimate was too low. Maybe you forgot annual expenses. Perhaps your entertainment category wasn’t realistic.
Make adjustments and try again.
It may take several months to develop a budget that accurately reflects your lifestyle.
Conclusion: Your First Budget Is a Draft
Here’s something worth remembering: your first budget will probably be wrong.
And that’s completely fine.
The purpose of your first month isn’t perfection. It’s awareness.
Every forgotten expense, unexpected purchase, and underestimated category teaches you something about your financial habits.
People who successfully budget for the long term aren’t necessarily people who never make mistakes. They’re people who notice what went wrong, make adjustments, and continue.
Think of your budget as a living document rather than a set of unbreakable rules.
Start small.
Track your spending for seven days. Automate a small savings transfer. Create a guilt-free spending category. Choose a simple budgeting method and give yourself time to learn it.
Your system doesn’t need to be complicated.
It simply needs to exist and be useful.
Money is a tool. Budgeting helps you decide how to use that tool intentionally instead of allowing your spending to happen automatically.
And if you’re ready to begin, don’t wait for the perfect spreadsheet.
Open your notes app today.
Write down your take-home income, fixed expenses, current savings, and major financial goals.
That’s your starting point.
The rest can be adjusted as you go.